What defines a high-risk PSP?
A high-risk PSP is a Payment Service Provider that supports merchants whose payment flows carry higher exposure to fraud and chargeback volume, while also facing regulatory scrutiny, settlement risk, or operating restrictions beyond standard retail categories. When a high-risk PSP evaluates another PSP connection, or when a high-risk merchant assesses a direct PSP relationship, the same practical questions apply across category experience and reserve terms, chargeback costs and fraud controls, and the ownership of integration support, reporting depth, and support.
That definition is the starting point. The harder work is telling the difference between a provider that understands the operating model and one that can technically onboard volume but cannot support the payment operation once disputes, declines, settlement questions, and route-level issues start moving.
For a high-risk PSP payment leader, the decision is rarely about one checkout connection. It covers payment coverage and backup capacity, the reporting and reconciliation model, and the ability to keep payment flows readable when one route underperforms. A provider may process transactions, but that alone does not answer the operational question: can the team explain what is happening by route, country, card BIN, decline code, chargeback reason, and settlement batch?
A useful evaluation starts with four areas. First, the PSP needs relevant vertical experience, because forex, online casino, gaming, subscriptions, and digital goods create different operating patterns. Second, the commercial terms must be readable beyond the headline transaction rate. Third, fraud and chargeback controls must match the risk profile. Fourth, the technical setup should reduce engineering time rather than create a permanent maintenance burden.
The strongest evaluation conversations stay concrete. Ask how many live provider connections or acquirer connections are available for your category. Then ask what the reserve terms mean for cash flow, how fallback routing works when a route has a payment issue, what the reporting shows, and who owns support when an incident affects approval rate or settlement.
Foundational questions: industry experience and specialization
Once the definition is clear, start with category fit. A high-risk PSP that has worked with subscription billing may understand recurring payments, trial abuse, refund pressure, and dispute timing, but that experience does not automatically transfer to online gaming or forex. Vertical knowledge matters because risk shows up in daily operations, not in a label.
Ask which high-risk merchant categories the PSP actively supports and which ones it avoids. The answer should be direct. If the PSP treats all high-risk categories as one commercial bucket, the discussion is already too thin. A serious provider should be able to explain how underwriting and transaction monitoring differ by business model, along with the reporting, chargeback handling, and settlement model.
Then ask how they support payment coverage. For a high-risk PSP or high-risk merchant, one approval path is fragile. A current route may work until a provider software change, acquirer policy change, technical incident, BIN-specific decline pattern, or regional issue reduces acceptance. Backup routes need to be connected and manageable before a payment issue, because an unconnected alternative cannot protect the payment flow during an incident.
From there, move to operational evidence. Ask what data they can show during a payment issue. You want breakdowns by provider connection and acquirer connection, with country, payment method, card BIN, decline code, and time period available in the same view. Without that detail, teams often move traffic before isolating the cause, which can hide the real pattern and create new settlement or approval-rate problems.
Also ask who at the PSP actually works with merchants in your category. Account management without payment operations depth is limited. You need people who can discuss routing and risk controls, settlement and chargeback exposure, and reconciliation and merchant onboarding in the same conversation.
Key terms for high-risk payment processing
Before the commercial and technical review, align the language. These terms shape the PSP conversation and keep the call away from broad promises that cannot be tested in operations.
High-risk PSP
A Payment Service Provider that supports merchant categories with higher fraud, chargeback, compliance, or settlement exposure. In evaluation, the key issue is category fit, not the label itself.
High-risk merchant
A merchant operating in a category such as forex, online casino, gaming, subscriptions, digital goods, or another regulated or chargeback-sensitive model. The risk profile usually affects underwriting, fees, reserves, reporting, and chargeback monitoring.
Reserve
Funds held back by the PSP or acquiring side to cover potential chargebacks, refunds, fines, or other exposure. A reserve can affect cash flow as much as the transaction fee, so the terms need to be clear.
Rolling reserve
A reserve held as a percentage of processed volume and released after a defined period. Ask how much is held, for how long, under what conditions it changes, and how release reporting works.
Chargeback
A cardholder dispute that can reverse a transaction and create fees, evidence requirements, and risk monitoring pressure. The PSP should explain how disputes are tracked, reported, and worked.
Fallback routing
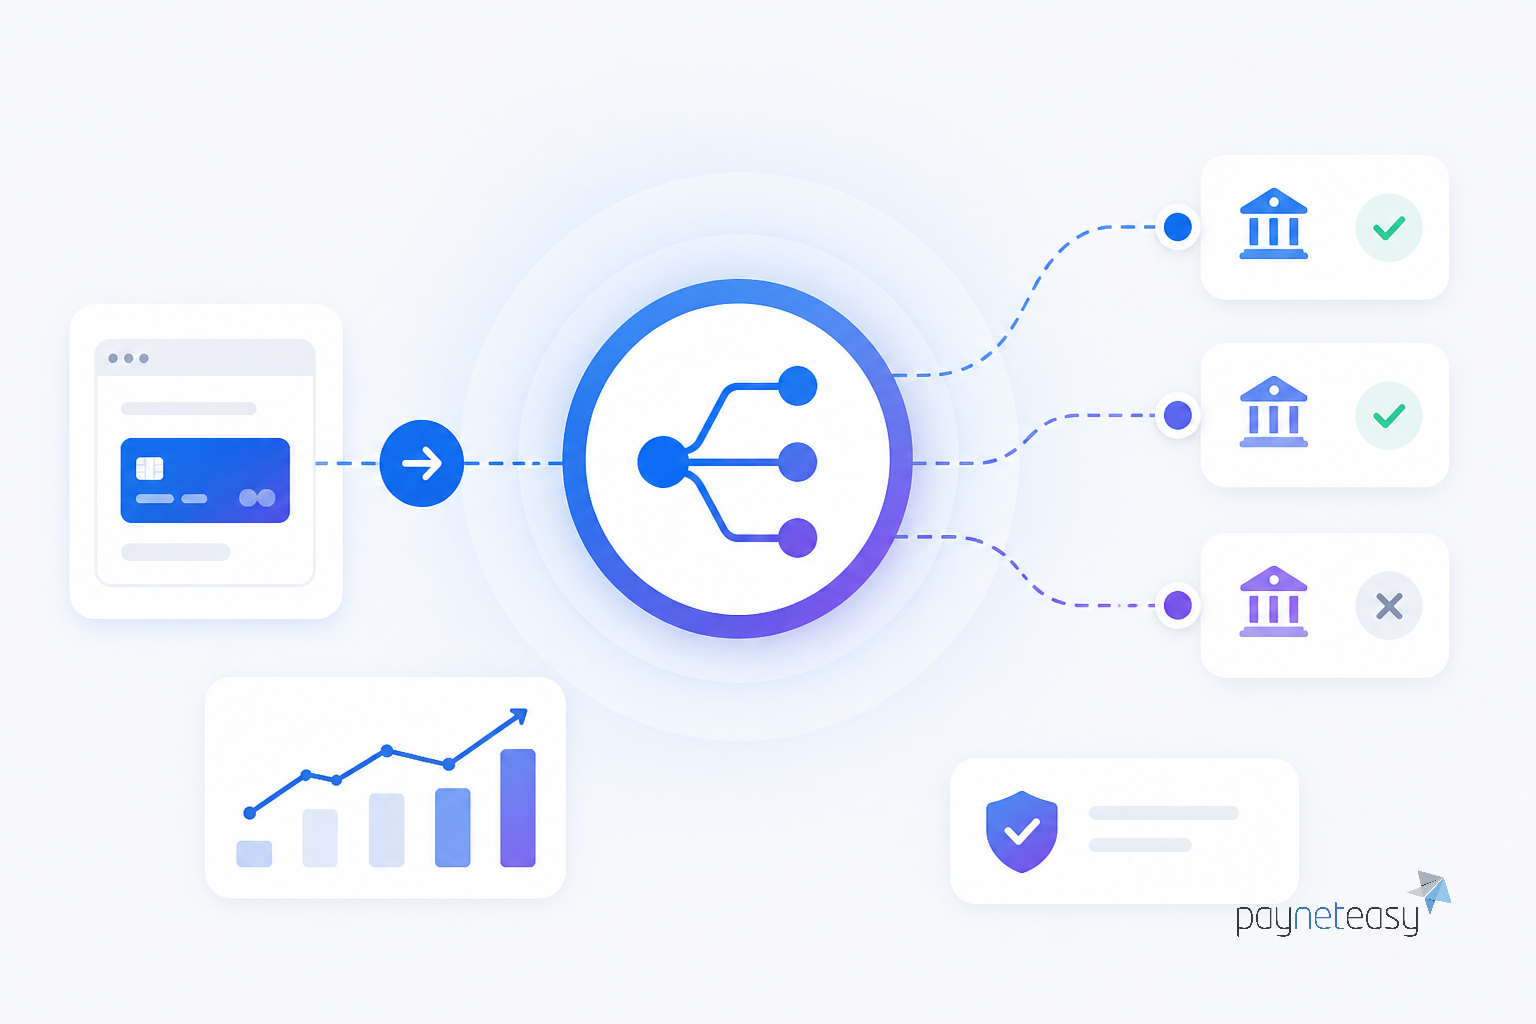
Routing logic that sends a transaction to another live route when the primary route cannot complete the payment or when business rules require another path. It only works if the backup route is already connected and tested.
Payment orchestration
A technology layer that helps manage payment flows across multiple provider connections or acquirer connections. For high-risk merchants, orchestration is often about coverage and traffic management, as well as reporting and reducing direct integration work.
Settlement and reconciliation
Settlement is the movement of funds according to the processing arrangement. Reconciliation is the process of matching transactions, fees, reserves, refunds, chargebacks, and payouts across systems.
Fee structures, reserves, and payout schedules
With the terms clear, move to the money. The headline transaction rate is only one part of the cost of a high-risk PSP relationship, and it is often the least useful number until the reserve, chargeback, payout, and technical costs are understood.
Ask for a written breakdown of every fee category before discussing volume commitments. That should include transaction fees, setup fees, monthly minimums, refund fees, chargeback fees, representment fees, currency conversion costs if applicable, payout fees, reporting fees, and any cost connected to additional payment methods or provider connections. If the PSP offers several pricing models, ask what operational behavior changes the cost. High chargeback volume, cross-border traffic, refund patterns, or specific payment methods may change the economics.
Reserves need special attention because they turn a pricing conversation into a cash-flow conversation. Ask whether the reserve is rolling, fixed, capped, or subject to review. Ask what percentage is held and how long funds are held. Also ask which events can increase the reserve, and what data is used in the review. A reserve that looks manageable at launch can become painful if the release terms are vague or if the PSP can change the amount without a clear trigger.
Payout schedules should be treated with the same seriousness. Ask when funds are paid and what can delay settlement. Then confirm how holidays and weekends are handled, and whether chargebacks, refunds, or reserve changes are netted before payout. Also ask how settlement files map to transaction-level reporting. If finance cannot reconcile processed transactions to payouts, the PSP has created an operating cost outside the fee schedule.
The harder question is how pricing behaves when you add payment coverage. High-risk PSPs and high-risk merchants often need more than one active route, but each additional payment path may bring its own costs, contract terms, technical work, and reporting gaps. Ask whether the PSP can manage multiple routes under one operating view, or whether each connection becomes another separate project for the payment team.
It is also fair to ask what happens when volume changes. A high-risk merchant can see sharp swings from campaigns, seasonal demand, new regions, or product changes. The PSP should explain whether pricing, reserves, risk monitoring, and payout cadence are reviewed by volume tier, chargeback rate, category, geography, or a mix of those factors. Do not accept a vague answer here. The point is not to negotiate every possible scenario in advance, but to know which events can change your economics.
Fraud prevention and chargeback management
After costs, risk controls decide whether the relationship can hold under pressure. A high-risk PSP relationship can look workable on pricing and still fail operationally if fraud controls are too blunt, chargeback handling is slow, or reporting does not show the pattern behind the problem.
Start with fraud screening. Ask what controls are available before authorization, during authorization, and after authorization. The PSP should be able to discuss risk rules and velocity checks, country and BIN logic, device or behavioral signals if used, manual review options, and how rules are changed. A generic claim that fraud tools exist is not enough. You need to know who configures them, how quickly rules can be adjusted, and what happens to approval rate when controls are tightened.
Then move to chargeback management. Ask how disputes are received and categorized, how they are reported, and who gets assigned to act on them. A high-risk merchant needs visibility into reason codes, affected products, transaction sources, customer cohorts, and routes. If the PSP only gives aggregate chargeback counts, your team may see the damage without seeing the cause.
Representment should be discussed in plain operational terms. Ask what evidence is collected, where it is stored, how deadlines are tracked, and which cases are worth fighting. Ask whether the PSP gives reporting that helps the team decide between representment and refund policy changes, checkout changes, traffic shifts, or fraud-rule changes. A chargeback operation that treats every dispute the same way usually wastes time.
Routing is part of risk control too. If one provider connection shows a decline pattern or chargeback issue in a specific country, the payment team should be able to investigate before moving traffic. The right question is: what does the PSP show before we change routing? You want payment operations to isolate the pattern by provider and route, then narrow it by country, card BIN, and decline code. Without that view, the team may shift traffic away from a route that is not actually the cause.
For merchants using 3-D Secure or other authentication flows, ask how authentication affects approval rate, fraud exposure, and customer drop-off in the supported regions. The PSP should explain the operational trade-off rather than treating authentication as a simple yes-or-no setting. For high-risk categories, strong authentication can help risk control, but poor configuration can also reduce acceptance or create support issues.
Risk teams and payment operations also need to work from the same view during an incident. Fraud, chargebacks, decline spikes, and settlement holds are connected in practice. If those teams operate in separate support queues with no shared view of the payment flow, the merchant or PSP payment operations team carries the coordination burden.
Technical integration and security compliance
After finances and risk, the next hurdle is implementation. Direct PSP integrations often look like one-time projects, but they become ongoing work when APIs change, routing rules need updates, reporting breaks, or a backup route has to be added under pressure.
Ask what integration method is available and how much engineering time the team must commit. The useful answer is specific: API scope, test environment, certification steps, error handling, webhook or callback behavior, reporting exports, reconciliation files, and support during launch. If the PSP cannot explain the launch path in operational terms, product and engineering teams may discover the real scope too late.
Backup capacity deserves its own technical review. Ask whether a fallback route is live and tested from the start, with monitoring and management in place, or whether it becomes a new integration project when the primary route has a problem. For high-risk payment flows, a backup route that is only a contract option is not payment coverage. It must be connected before it is needed.
Security compliance should be handled without marketing language. Ask about PCI DSS scope and token handling, access controls and audit practices, data retention, and how operational users access payment data. Payneteasy, for example, is PCI DSS Level 1 compliant, and its technology includes reporting and reconciliation, more than 1,000 integrations, capacity for up to 10 million transactions per day, and 99.95% verified uptime. Those figures matter because payment infrastructure is judged during ordinary operations and during incidents.
You should also ask how quickly a new PSP connection can be added when the business needs another route. Payneteasy states that Payment Channels can add a new PSP connection within 1 to 2 weeks on top of more than 1,000 existing integrations. That capability is relevant when a high-risk PSP or high-risk merchant needs more payment options without turning every provider connection into a separate internal build.
Support, account management, and SLAs
Once the connection is live, day-to-day support becomes the test. Payment operations need clear ownership when approval rate changes, settlement does not match reporting, chargeback volume rises, or a provider connection behaves differently from expected.
Ask who handles live payment issues and how escalation works. A general support desk may be fine for routine tickets, but high-risk payment flows need account management that understands routing and risk controls, reconciliation and settlement, and merchant onboarding. The PSP should identify the support model, response expectations, incident process, and the information your team must provide when raising a case.
Service levels should cover more than uptime. Ask how the PSP defines uptime, what is excluded, how incidents are communicated, and whether status updates include operational impact. Also ask about reporting availability and settlement file delivery, API performance, and support response during high-volume periods. For a high-risk merchant, a technically available service can still create serious problems if reporting is delayed or routing visibility is poor.
A practical test works better than a generic SLA discussion. Give the PSP a real payment issue from your history and ask how they would investigate it. Their answer will show whether they think like payment operations or only like a vendor managing tickets.
Using this framework for your PSP evaluation
Once you have the full set of questions, use them as an operating review rather than a simple checklist. Not every answer has the same weight. For a high-risk PSP, the main decision is whether the provider can support the operating reality behind the payment flow. For a high-risk merchant, the same standard applies to the direct PSP relationship.
Build the evaluation around evidence. Ask for written terms, sample reports, reserve mechanics, payout examples, integration steps, escalation paths, and a clear view of how routing and fallback routing are managed. Use the same scenario across each PSP conversation so the answers are comparable: a decline spike in one country, a chargeback increase on one product, a settlement mismatch, or the need to activate backup capacity before a provider issue affects revenue.
The honest trade-off is that high-risk processing usually requires more documentation, more monitoring, and more controls. That is not automatically a problem. The problem is accepting unclear terms, weak reporting, or a technical setup that leaves the payment team carrying the burden of every new connection and every payment incident.
Good PSP evaluation is disciplined. The provider should understand the vertical and explain the economics. It should also show how risk is managed, reduce integration strain, and support payment operations with enough detail to make decisions before traffic is moved. If those answers are vague, the risk has not disappeared. It has moved into the operating model.